Fundraising tips from serial entrepreneur and Tradestars founder and CEO Roy Shaby
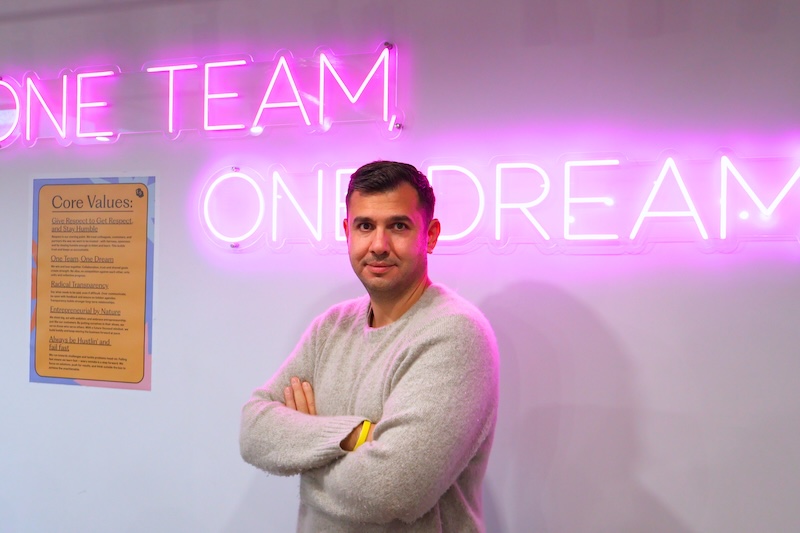 [Pictured above] Roy Shaby, founder of Running Sushi, co-founder of FoodStars and founder and CEO of Tradestars.
Roy Shaby, the dark kitchen serial entrepreneur who took his first business, Running Sushi, from a 3k personal investment to a 300k revenue outfit in one year, sold his second dark kitchen business to Uber co-founder Travis Kalanick, and now runs a £4m multi-site space provider, Tradestars, knows a lot about getting businesses off the ground. Here, he shares his insider tips on fundraising for startups.
1. Have market fit
Investors today are very wary of product-market fit, and they want to see real-life examples of whether you’re able to sell what you are selling. Try to identify the market fit early on, and even if it doesn’t work out for you, you can pivot. When you’ve already invested large sums of capital into something you believe could work, but then you have to pivot, you’re out of funding – and that’s not a good place to be in. There are very cost-effective ways of figuring it out. Even launching a small Google Ad campaign with a homepage to say, coming soon, is a good place to start. You can identify the volume of people that will come through for your product, and maybe even interview them, do case studies and figure it out. They will tell you what they need. Try and figure it out before you fundraise because when you walk into a room with solid data of this can sell or this can work, it’s a different conversation because if you don’t have it, all that investors are going to tell you to do is go and do it and then come back to them.2. Have the receipts
I bootstrapped my first business with very little money, and if I had wanted to go and raise money for it, I could have come up with the receipts, you know, that I’m selling, it’s working. It’s live. It’s online. Then you can do an analysis. So, okay, if I scale it from here, this is what I can do, that’s really, really important. It’s powerful to walk into a boardroom with potential investors and say I’m already selling, and you can either join me or you can get left behind, and I’ll go to the next investor. You create a bit of FOMO.3. Find your customers
My advice to every aspiring entrepreneur who comes to me with a deck is to go and try and find customers. I spoke to someone recently who has been trying to raise money for a product for over a year and is struggling. They can’t get people to commit now because they need the funding in place to create the product that they’re offering. It’s a hardware product, not software. So, I advised them to get letters of intent [LOIs] from their potential customers. So you can bring it into the boardroom and say, look, I’ve got a list of ten potential customers. Each of them is worth X amount of dollars per transaction. They’re ready to work with me as soon as I have the funding and I can create it, then I can go to work.